Join WhatsApp Channel
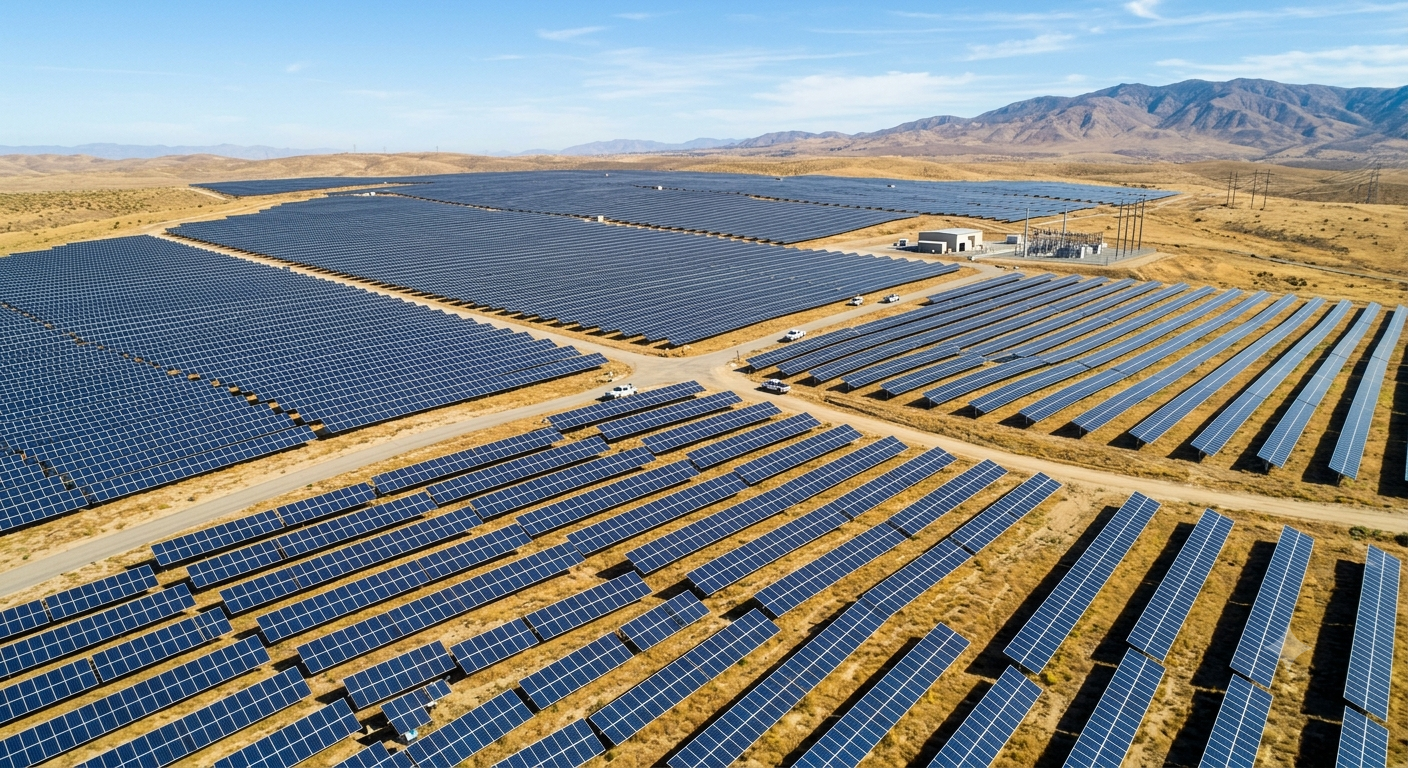
India’s accelerating shift to renewable power is heading towards a new constraint: whether the electricity grid can absorb the capacity being added without increasing curtailment, transmission congestion and system instability, a FICCI-Nangia report has warned.
With non-fossil sources accounting for more than half of installed generation capacity and peak electricity demand reaching a record 256 GW in April 2026, the report projects that grid stability will increasingly determine how much of India’s planned renewable capacity can actually be delivered to consumers.
More than 23 GW of renewable capacity was curtailed between May and November 2025 for grid-security reasons, while system frequency was outside the prescribed Indian Electricity Grid Code band for nearly one-fifth of May.
The immediate concern is that the mismatch between generation additions and grid infrastructure could widen as India adds more solar and wind capacity.
Industry estimates cited by the report suggest more than 35 GW could face curtailment risk in fiscal 2026-27 because of limited long-term transmission access. India has delivered only about 80 percent of its annual transmission targets over the past five years, adding to the risk that generation capacity could be commissioned faster than the network required to evacuate it.
That could have consequences well beyond power-system operations. Renewable projects facing repeated transmission constraints may generate less electricity than their installed capacity implies, potentially affecting project revenues, financing assumptions and returns on investment.
“India’s clean energy transition has moved from a policy commitment to a financial reality where investors, lenders, and rating agencies are now pricing grid stability directly into their decisions,” Suraj Nangia, managing partner at Nangia Group, said.
“A grid that cannot keep pace with the capacity it has already built is no longer just an engineering challenge. It is a capital-allocation risk for the entire sector,” he said.
The FICCI-Nangia report, Grid Stability in India: From Diagnostic Assessment to a Reform and Implementation Roadmap, released at the Indian Power Sector Conference in New Delhi, sets out 14 priority actions through 2030 covering transmission, storage, system strength, market design, forecasting, cybersecurity and institutional capacity.
Storage becomes critical
The pressure on the grid is expected to increase as the generation mix changes.
Conventional coal, gas and hydro generators provide physical inertia through their spinning turbines, helping the system withstand sudden changes in supply and demand. Solar plants and much of the new wind capacity are connected through inverters and do not automatically provide the same stabilizing response.
That makes storage and other grid-support technologies increasingly important as renewable penetration rises.
Battery storage expanded from 0.78 GWh in December 2025 to about 8.5 GWh by June 2026, but the report says India needs to reach 73.93 GW, or 411.4 GWh, of battery storage by fiscal 2031-32.
The investment requirement will be substantial. The report estimates ₹5 trillion to ₹6 trillion of transmission investment through fiscal 2031-32, alongside about ₹3.49 trillion for battery storage and ₹1.29 trillion for pumped storage.
The scale of future demand makes the timing of that investment critical. India is expected to have around 1,121 GW of installed generation capacity by 2035-36, including about 786 GW from non-fossil sources, while peak demand is projected at 459 GW.
The issue, therefore, is increasingly one of flexibility rather than simply capacity.
Transmission could determine renewable utilization
The report calls for generation, transmission and storage projects to be planned and commissioned against a common timetable, an approach intended to reduce the risk of renewable plants being completed before evacuation infrastructure is available.
It also recommends greater use of grid-enhancing technologies such as dynamic line rating, advanced conductors, reconductoring and phase-shifting transformers to increase the carrying capacity of existing networks.
For renewable-heavy regions such as Rajasthan and Gujarat, the report proposes additional measures to strengthen the grid, including synchronous condensers and STATCOMs at locations where low system strength could constrain renewable integration.
The implications extend to electricity markets. The report argues that services such as system strength and grid-forming capability should increasingly be valued and paid for rather than treated solely as technical compliance costs for developers.
That would potentially create new revenue streams for batteries, flexible generators and other technologies capable of providing grid-support services, while giving system operators more tools to manage periods of high renewable output and rapidly changing demand.
Coal plants face a new role
The transition is also likely to change the role of India’s conventional generating fleet.
Rather than operating primarily as baseload generators, coal plants may increasingly be required to ramp up and down to compensate for fluctuations in solar and wind generation. The report proposes thermal flexibilization, including a target of operating plants at a minimum technical load of 40 percent by 2030.
This could create additional investment and operating costs for older plants while increasing the value of generators capable of responding quickly to changes in system conditions.
At the distribution level, the growing penetration of rooftop solar and solar pumps will require utilities to have much greater visibility over millions of smaller generation assets. The report proposes scaling Distributed Energy Resource Management Systems beyond pilot projects to manage those resources.
Cybersecurity becomes part of grid stability
The report also treats cybersecurity as an increasingly important component of physical grid resilience as more power-system functions become digitally controlled.
It calls for mandatory model certification and standardized modelling libraries to improve the ability of operators and regulators to identify stability risks before projects are commissioned. It also highlights compliance with the CEA Cyber Security in Power Sector Regulations, 2026, including the requirement for rapid reporting of cyber incidents.
Artificial intelligence could play a larger role in forecasting and system monitoring, using India’s wide-area monitoring infrastructure, which includes more than 1,740 phasor measurement units.
But the report stresses that digital tools will need to operate alongside strong human oversight and established system-protection mechanisms.
Ghosh said the operating environment had already changed fundamentally as non-fossil capacity expanded.
“We now operate alongside close to 283 GW of non-fossil capacity, over half the country’s installed base and most days, inside a control room, that feels less like comfort and more like coping,” said Arindam Ghosh, partner, energy consulting, Nangia.
The report’s central warning is consequently about the next phase of India’s energy transition: adding renewable megawatts will not by itself deliver equivalent quantities of usable electricity.
If transmission, storage, flexibility and grid-support capabilities do not expand alongside generation, renewable curtailment could rise even as installed clean-energy capacity reaches new records.
For investors and power companies, that makes the pace of grid modernization increasingly important to the economics of India’s renewable build-out. For policymakers, the challenge is shifting from meeting capacity targets to ensuring that the increasingly renewable-heavy system can operate reliably when that capacity is actually needed.